Financing advisory · Mumbai · New York
We make Indian projects bankable.
RupyAI brings New York structured-credit discipline to Indian companies raising debt and equity. We model the cash flows, score the risk, build the file that banks and investors decide on, and stay with you until the money is in.
Start a conversationSee how we work
New YorkMumbai
Why India
A large share of the world's growth now comes from India. The capital to fund it is still catching up.
- 17%of world growth
- India's expected share of global economic growth in 2026.IMF
- 6.4%growth forecast
- For the year to March 2027, among the fastest of the large economies.IMF
- ₹30lakh crore
- Credit that smaller businesses need and cannot get. About US$310 billion.SIDBI
- ₹2.5lakh crore
- Loans securitised in the year to March 2026, a record. About US$26 billion.ICRA
For companies raising capital
A structure, a model and a score that a bank or an investor can test line by line, so the decision comes sooner.
For lenders and investors
Indian real-asset and loan-pool credit, presented the way a New York credit committee expects: every number traced to a document.
Sources: IMF World Economic Outlook updates, 2026. SIDBI, Understanding Indian MSME Sector, May 2025. ICRA, April 2026. Dollar figures at about ₹96 per dollar. Forecasts can change.
What we do
Four kinds of work. A mandate can cover one of them or all four.
- Financing strategy and capital structure
- We work out how much debt and equity a business or project can carry, and in what order to raise them. The answer comes from the cash flows and the security available, and we write it down as a structure a lender can assess.
- Cash-flow modelling and debt sizing
- We build a period-by-period model of revenue, costs, tax and debt service from the contracts and the operating assumptions. Debt is sized to the cover ratios lenders apply, in a base case and in downside cases.
- Risk scoring and independent diligence
- We read the full document set and score the risks a credit committee will raise, from offtake and supply to construction, approvals and sponsor strength. Each score comes with the evidence behind it and the gaps still open.
- Lender-ready documents and arranging Indian debt
- We prepare the information memorandum, the model and the data room in the form Indian banks and institutional lenders expect. We then approach suitable lenders in India and manage the questions that follow.
How we work
Five steps, in this order. Each one feeds the next.
-
01
Read every document
We start with the full set: contracts, approvals, land papers, financial statements, technical reports and existing loan documents. We list what exists, what is missing and what conflicts.
-
02
Rebuild the model
We build our own cash-flow model from the source documents. Every input traces to a page in the document set, and the sponsor's spreadsheet serves as a cross-check.
-
03
Score the risk
We score each risk area against written criteria and record the evidence. The result is the RupyAI Score, and it shows where a lender or investor is likely to push back.
-
04
Fix what blocks financing
Weak points are dealt with before any lender sees the file. That can mean a firmer offtake term, a missing approval, more sponsor equity or a smaller loan.
-
05
Go to lenders once
The proposal goes out when the file is complete. Lenders see one consistent set of documents, one model and one set of answers.
Two cities
The work happens in India. The method comes from the market where loan pools are priced and financed every day.
India · IST
Mumbai
The company is registered here as Yuktimetrics credTechno Pvt Ltd. Engagements are signed in Mumbai under Indian law, and the work with sponsors, banks and institutional lenders takes place in India.
United States · ET
New York
The founder is based here. Cash-flow modelling, structuring and the risk method are led from New York and follow the practice of the US structured-credit market.
Where we focus
Sectors in India where repayment comes from contracted or recurring cash flow and from the asset itself.
Bioenergy and compressed biogas
Plants that turn crop residue, press mud, cattle dung or municipal waste into gas and organic manure. Repayment depends on feedstock supply, gas offtake and plant uptime.
Renewable and distributed energy
Solar, storage and on-site power sold under contract to commercial and industrial users. Repayment depends on the tariff, the buyer's credit and the energy generated.
Infrastructure-linked receivables
Payments due under concessions, annuities and long-term service contracts. Repayment depends on the paying authority and the contract terms.
MSME and asset-backed lending platforms
Lenders and platforms that originate secured small-business loans, equipment finance and similar pools. Repayment depends on collections, losses and servicing.
Where this is going
- Today
Project and corporate financing. Advisory for Indian sponsors raising debt and equity for real assets.
- Next
Funding for MSME lenders. Credit lines sized on how a lender's loan book has actually performed.
- Then
Securitisation of Indian loan pools. Pass-through certificates and direct assignment, arranged with partners licensed for each step.
The second and third steps are in development. They are plans, not services offered today.
Tools
We build our own analytical tools. The deal desk is our internal workspace: each deal has one page that holds the documents, the model, the risk score and the plan.
- Cash-flow engine
- Projects revenue, costs, tax and debt service period by period, and reports the cover ratios under each scenario.
- RupyAI Score
- One score out of 100 for each deal, built from twelve risk areas, with the evidence for every point listed beside it. Over time it becomes a lending score for Indian small-business credit, trained on how loans actually perform.
- Document library
- Files every source document by type, so that each number in the model points back to a page.
Debt service cover ratio by operating year
Illustrative data- Base case
- Downside case
- 1.0x threshold
Show the sample numbers as a table
| Year | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 10 |
|---|---|---|---|---|---|---|---|---|---|---|
| Base case | 1.34 | 1.38 | 1.36 | 1.42 | 1.45 | 1.44 | 1.49 | 1.52 | 1.55 | 1.58 |
| Downside case | 1.08 | 1.04 | 0.94 | 0.98 | 1.06 | 1.10 | 1.12 | 1.15 | 1.17 | 1.20 |
The tools are internal and still being developed. They organise the analysis and keep it traceable. The judgement stays with a person.
About
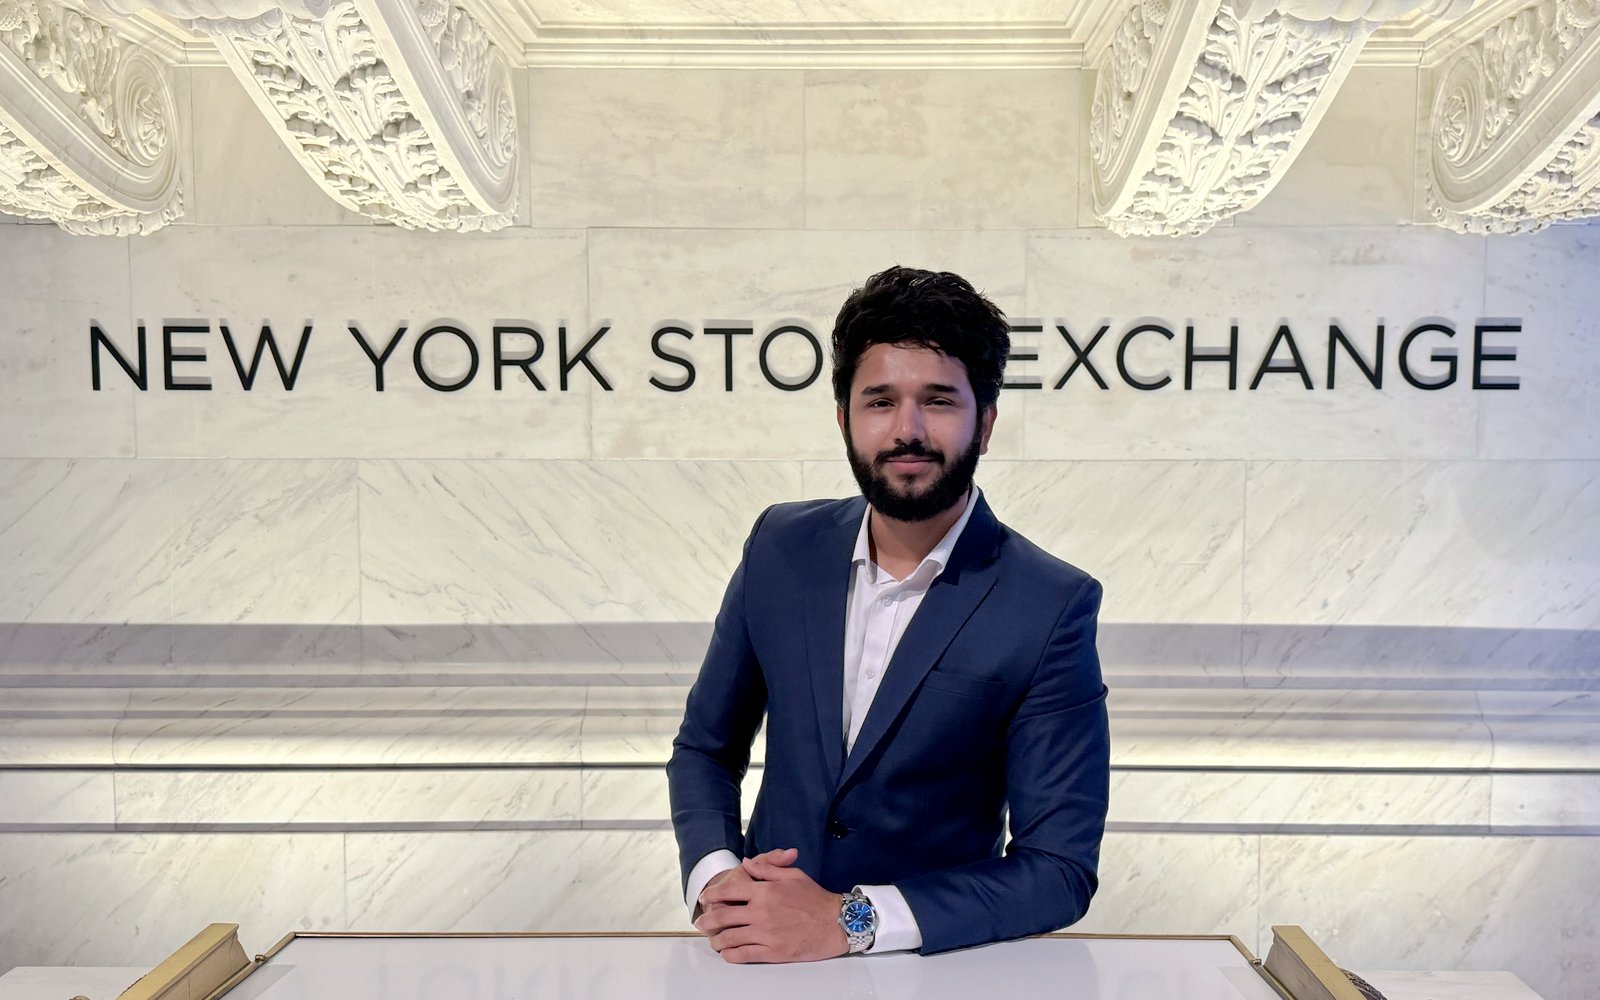
RupyAI is led by a New York capital-markets professional working where structured credit meets AI.
Manish Singh has spent his career on securitised credit: pricing loan pools, modelling prepayments and defaults, and structuring the bonds they back. He is Manager, Capital Markets at a US financial firm.
- Intercontinental Exchange (NYSE)Senior Financial Engineer, structured-product indices
- Simplify Asset ManagementInvestment Associate
- MorningstarQuantitative Analyst, ratings of securitised products, Mumbai
- UCLA AndersonMaster of Financial Engineering
- MIT xPROArtificial intelligence programme
RupyAI is his own venture. It is separate from his current and former employers, and nothing on this site speaks for them.
Manish Singh · Founder, RupyAI · LinkedIn
Insights
Short explainers on how lenders look at cash-flow-backed deals.
-
How lenders size debt on a project: DSCR in plain words
What the debt service coverage ratio measures, how it turns projected cash into a loan size, and why the downside case decides.
-
India's compressed biogas scheme: what a financier checks first
The policy creates demand for gas. A lender still asks six questions about one specific plant.
-
What a risk scorecard does that a pitch deck cannot
A deck argues for a deal. A scorecard applies the same questions to every deal and records what the documents show.
Questions
What is RupyAI?
RupyAI is a financing advisory business. It brings New York structured-finance methods to cash-flow-backed businesses and real assets in India, and it builds its own analytical tools.
Is RupyAI the same as Rupya.ai?
Yes. RupyAI and Rupya.ai are the same business. The name is also written Rupy AI, Rupy.AI and Rupya AI. The website is rupy.ai, and rupya.ai points to it.
Who founded RupyAI?
RupyAI was founded by Manish Singh, a New York capital-markets professional working in structured credit and AI. He was previously Senior Financial Engineer at Intercontinental Exchange, the parent of the New York Stock Exchange, and worked earlier at Simplify Asset Management and at Morningstar in Mumbai. He holds a Master of Financial Engineering from UCLA Anderson.
What does RupyAI do?
RupyAI advises Indian companies and project sponsors on how to finance, with debt and with equity. The work covers cash-flow modelling, the RupyAI Score for risk, debt sizing, capital structure, lender-ready documentation and arranging debt from Indian banks and institutional lenders.
Where is RupyAI based?
RupyAI works from two cities. The company, Yuktimetrics credTechno Pvt Ltd, is registered in Mumbai, where engagements are signed and the work with sponsors and lenders takes place. The founder is based in New York, where the modelling and structuring are led.
Is RupyAI a lender or broker?
No. RupyAI is an advisory business. It does not lend money, it is not a broker-dealer or an investment adviser, and it does not offer or sell securities. It advises companies on financing and helps them approach Indian banks and institutional lenders, who make their own credit decisions.
Contact
Tell us what the business does, what you want to finance and roughly how much. Two paragraphs are enough to start. Manish reads every message himself.
manish@rupy.ai